


I sat in on their Hot Chips pre-brief Friday, and this note publishes the minute that embargo lifts.
Groq LPX is in full production. We said late Q3; it is shipping now. Spectrum X Multiplane is in silicon. SpaceX AI is putting Vera into production at gigawatt scale behind Grok. Wednesday grades the rest.
Five Beats, Read Honestly
NVIDIA has beaten its own revenue guide five quarters in a row: $1.1 billion over, then $1.7, $3.0, $3.1, and $3.6 billion last quarter. The beat rate peaked at 5.6 percent five quarters ago and has compressed three straight. Either the company is learning to guide closer to its own reality at enormous scale, or, in a supply-constrained year, shrinking upside is just what a supply cap looks like.
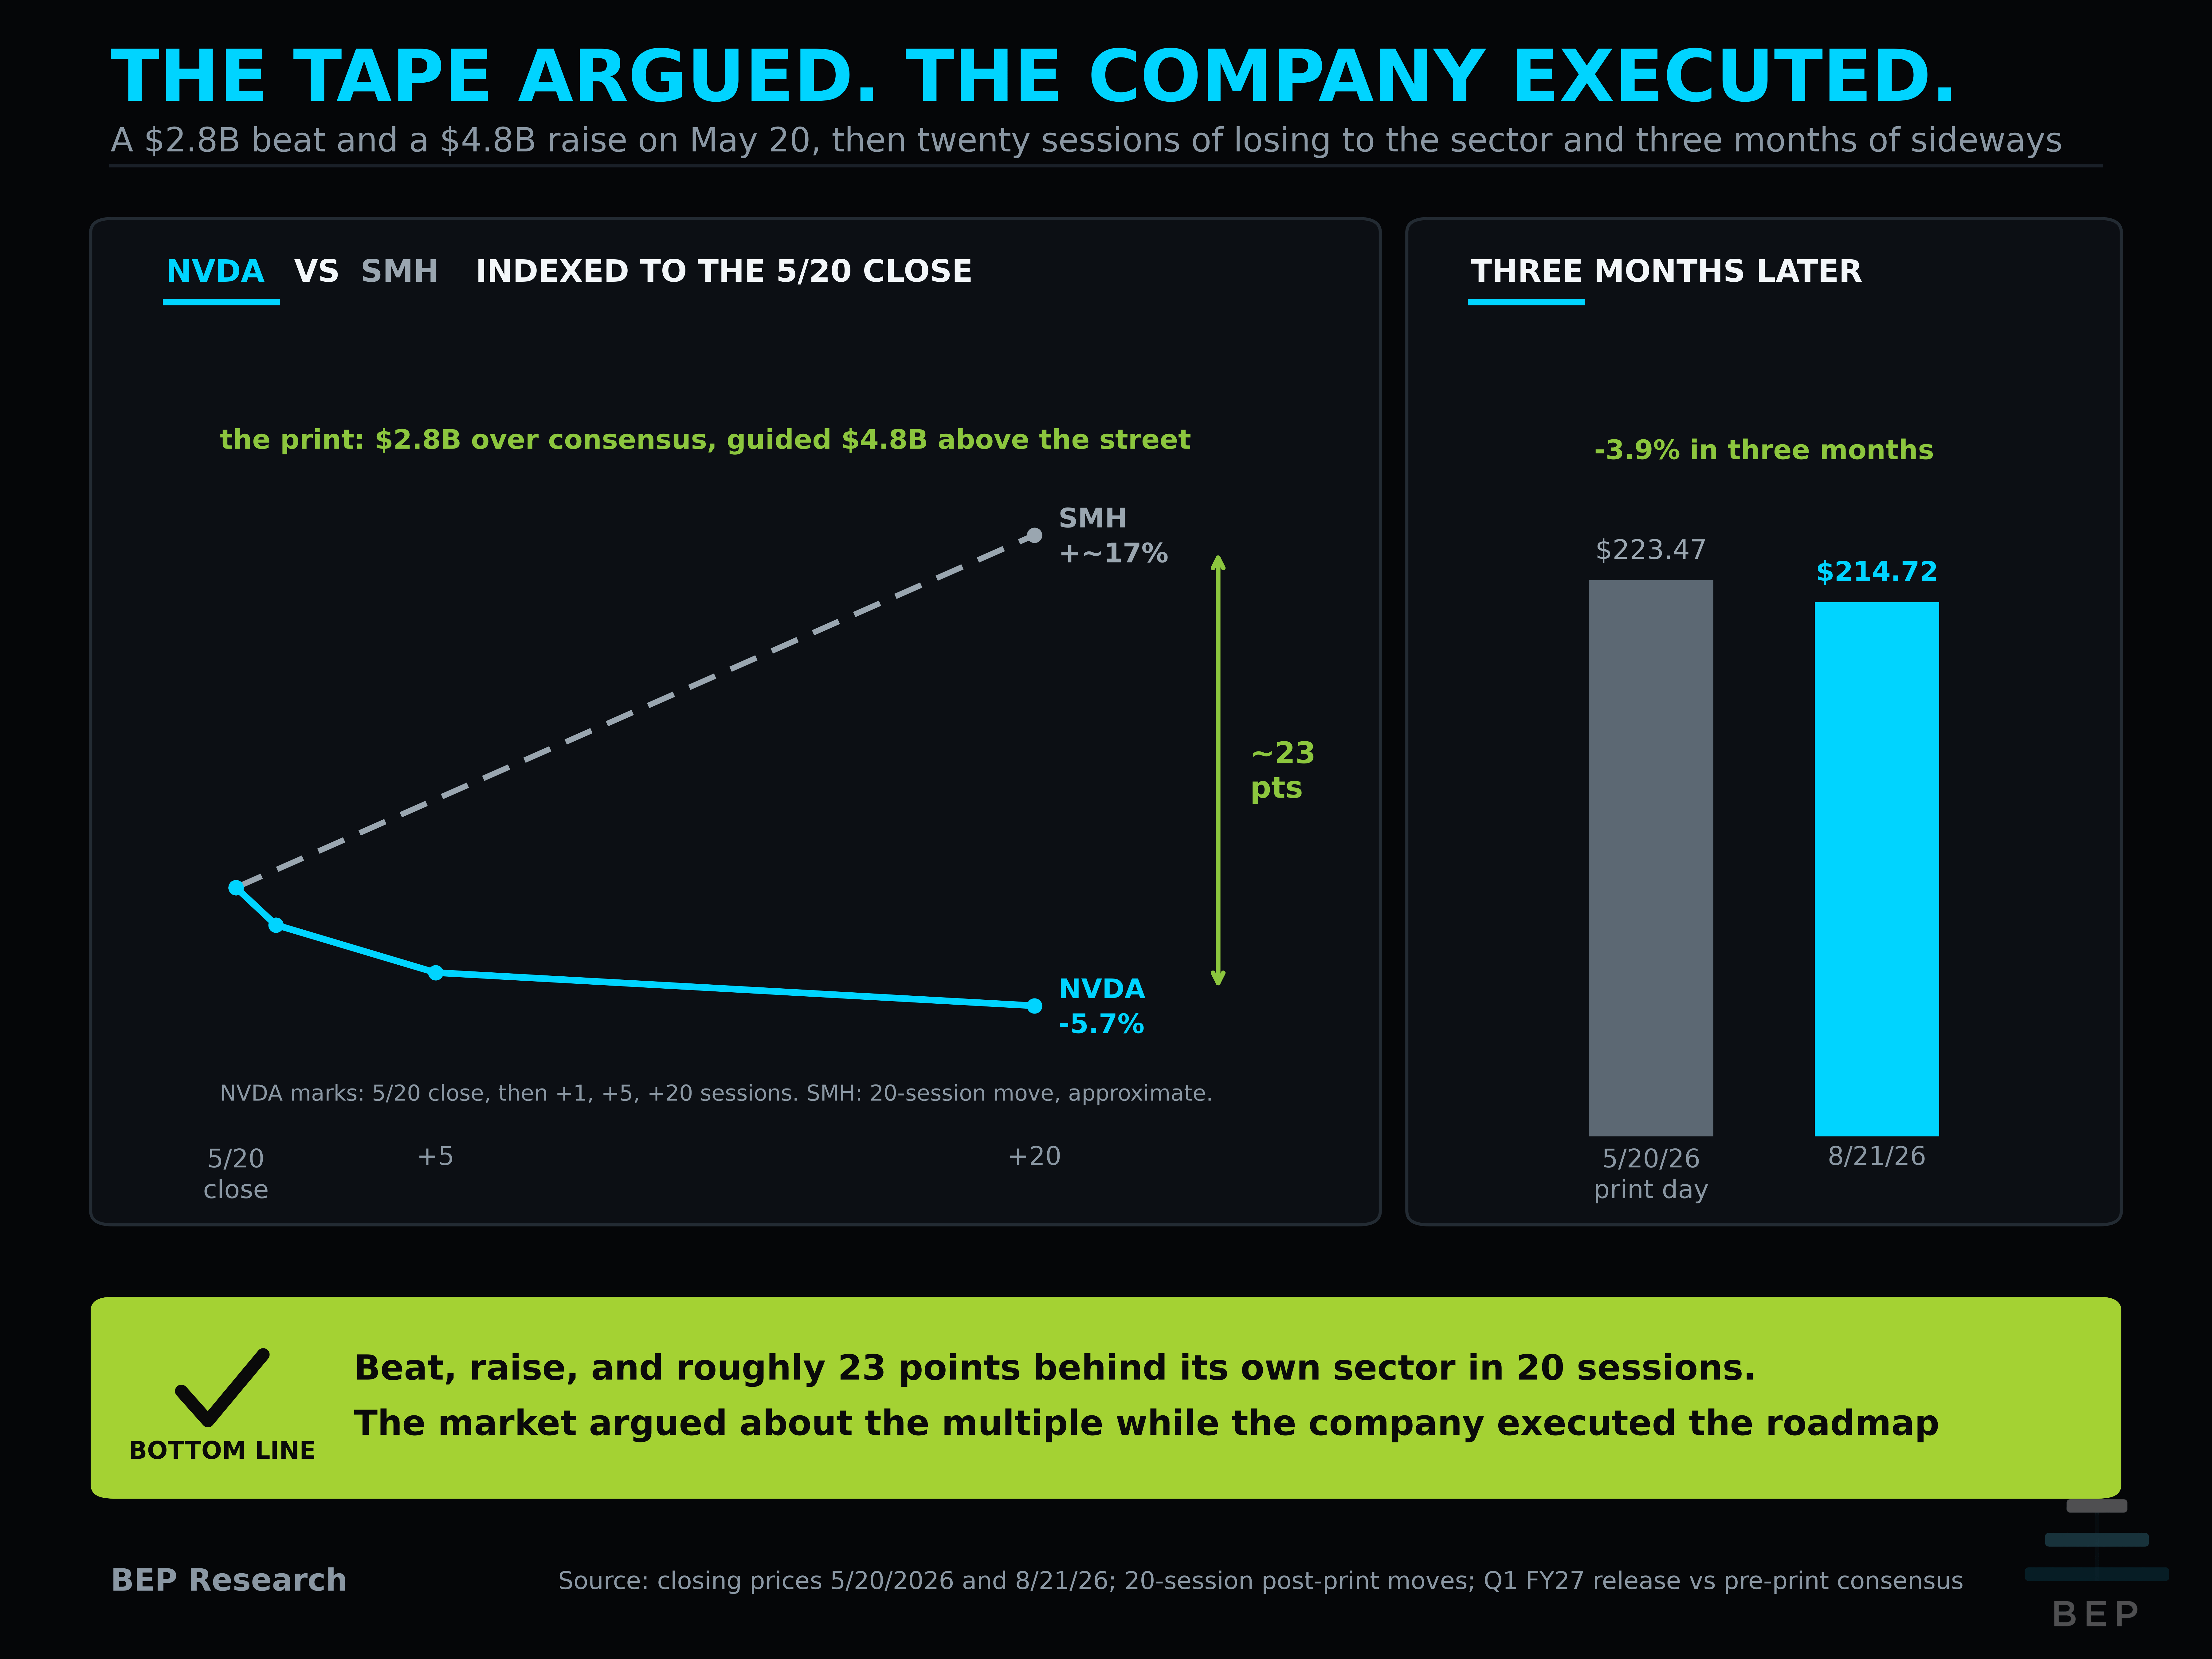
And May is the tape warning: $3.6 billion over its own guide, $2.8 billion over street, and a $4.8 billion raise, and the stock still lost roughly 23 points to the SMH in twenty sessions, three months of sideways since, $223.47 on print day to $214.72 on Friday. Our read is Rubin timing, first production shipments moving to Q3.
NVIDIA reports Wednesday: results after the close, call at 2pm Pacific, middle of Hot Chips week. This is the first Audit: dated claims, marked to what NVIDIA has printed since, and what Wednesday can still break. The Token Dollar loop, the optics read, the collateral thesis, the roadmap and the margin line all report this week.
Everyone is already expecting another blowout number. Our own group chats went into the week at portfolio highs, calling new all-time highs before earnings, revenue-is-exploding as the base case, while the indices sat red. Sentiment like that is its own bar; the published consensus sits near $91.9 billion on the 42-analyst compilation.
Run the cadence on the $91.0 billion guide and you get $94 to $96 billion. That is a BEP cadence estimate, not a claim about what the marginal buyer carries. A $92 or $93 billion print would beat consensus on every headline and still read light against the pattern.
At $214.72, the close on Friday, August 21, NVIDIA is a $5.2 trillion company at roughly 33 times trailing earnings, about 24 times this fiscal year’s (FY27) consensus earnings. You’re still paying for a lot of untapped revenue potential: the street’s own compilation has revenue near $394 billion this fiscal year, up more than 80 percent, with next year’s estimates centered near $560 billion and running as high as $710 billion. At that price and multiple it still looks inexpensive to us for a business producing this much free cash flow. What breaks it is not Wednesday’s beat. It is a break in margins, meaningful competition, or problems shipping products. Wednesday reads on all three.
That is the free half: the cadence math and the tape. Behind the paywall is the audit itself: the board, every claim dated and marked to what NVIDIA has printed since; the shell put, the 8-K’s $105 billion read at the megawatt and our threshold on the minimums that land with Wednesday’s 10-Q; the three Hot Chips answers marked against the lines they hit; the scorecard, including the one line that can grade against us; Thompson’s bear graded on the line he actually named; and the three states we will call the print by on Wednesday night, stated before the fact.
